How currency exposure works
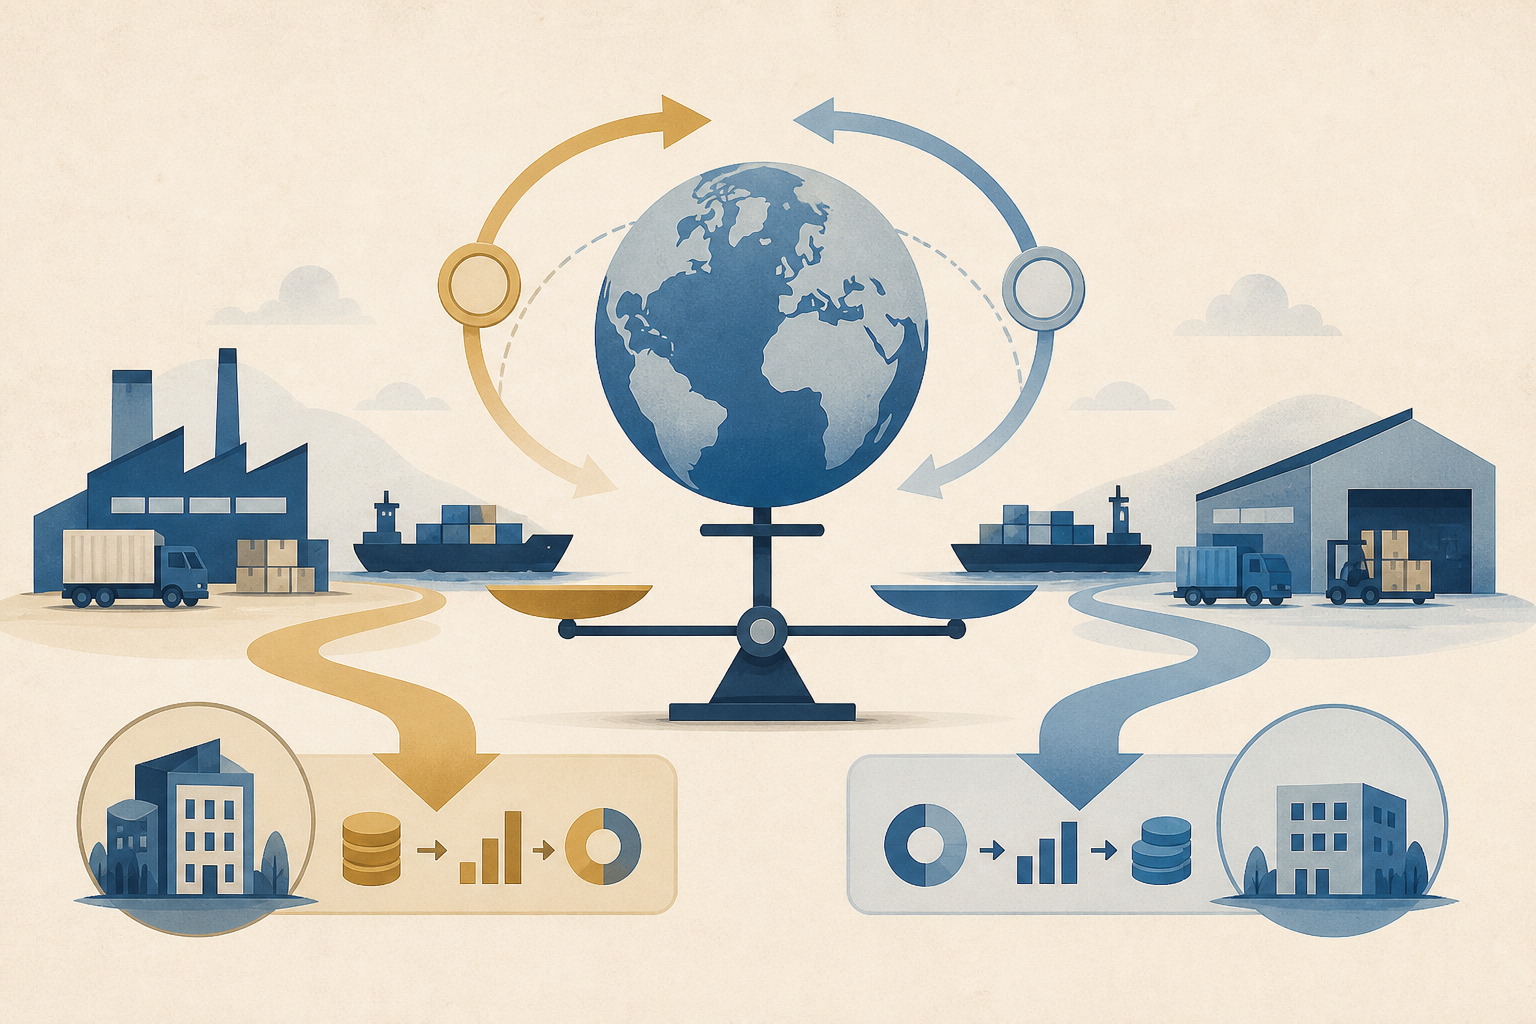
An exchange rate is the price of one currency in terms of another. The effect of a currency move depends on where a company earns revenue and pays costs.
Separate revenue and cost currencies
An exporter may benefit when overseas revenue translates into more home currency, but imported materials can offset that benefit. Importers need to compare costs with pricing power.
Translation versus transaction effects
Currency moves interact with rates, trade conditions, and economic expectations. Review revenue regions, cost currencies, hedging policy, and cash flow rather than relying on one direction alone.
A hypothetical exporter
A hypothetical exporter that earns dollars may report more translated revenue when its home currency weakens. But if its inputs and debt are also dollar-denominated, costs and interest can rise too. Local pricing, sales volume, contract currency, and hedge maturities determine when and how much reaches reported results.
Review hedging notes
In filings, identify revenue by geography, production locations, major cost currencies, foreign-currency assets and liabilities, derivative maturities, and hedge accounting. Compare the currency effect in cash flow with changes in operating margin. Management sensitivity analysis should be read with its exchange-rate assumptions and scope.
Sensitivity and timing
Currencies can affect earnings, discount rates, import prices, and capital flows at the same time. A currency direction alone cannot establish a share-price effect, and hedging can add cost and counterparty risk even as it reduces some volatility. State the rate date and reporting currency in comparisons.