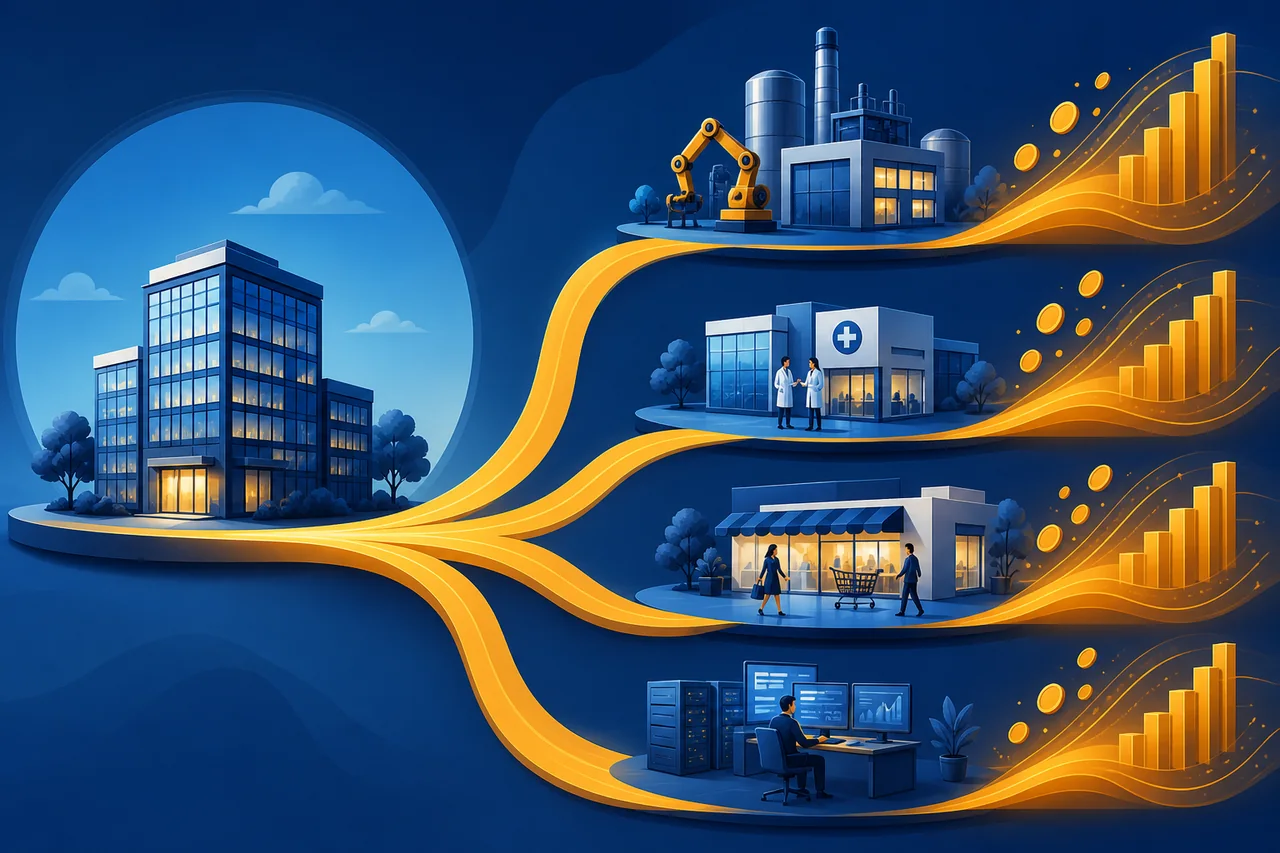
Several businesses inside one total
A company containing manufacturing, services, and finance businesses cannot be understood fully through consolidated revenue and operating profit. Segment disclosure shows which activities create growth and earnings and which consume capital. A strong total can hide weakness in the core segment, and a weak total can hide a promising smaller operation.
How segments are defined
IFRS 8 bases operating segments on the information management reviews internally. Start with whether the company organizes around products, regions, or customer groups and why some activities are aggregated. When the organization changes, check whether earlier periods were recast so the timeline remains comparable.
Growth and profit contribution
Place external revenue, growth, margin, assets, and capital expenditure by segment on one page. A fast-growing unit that still loses money has a different role from a mature unit producing cash. Avoid applying the consolidated growth rate or margin to every business inside the company.
Internal sales and shared costs
Sales between segments disappear on consolidation, and headquarters cost may not be allocated to an operating unit. Use the reconciliation to explain why the sum of segment profit differs from consolidated operating profit. If management's segment measure excludes depreciation or stock compensation, keep it separate from the accounting result.
Geography and customer concentration
Geographic revenue, non-current assets, and dependence on major customers may appear outside the main segment table. Concentration in one customer or country adds renewal, regulatory, and currency exposure. Confirm whether geography follows the customer's location or the reporting entity's location.
Build a consistent history
Build three to five years of segment revenue, profit, and assets on a consistent basis and annotate every classification change. Then test whether the unit described as a growth engine actually contributes to consolidated earnings and cash over time. Segment analysis is a habit of separating different economic engines, not a shortcut for finding a hidden winner.