
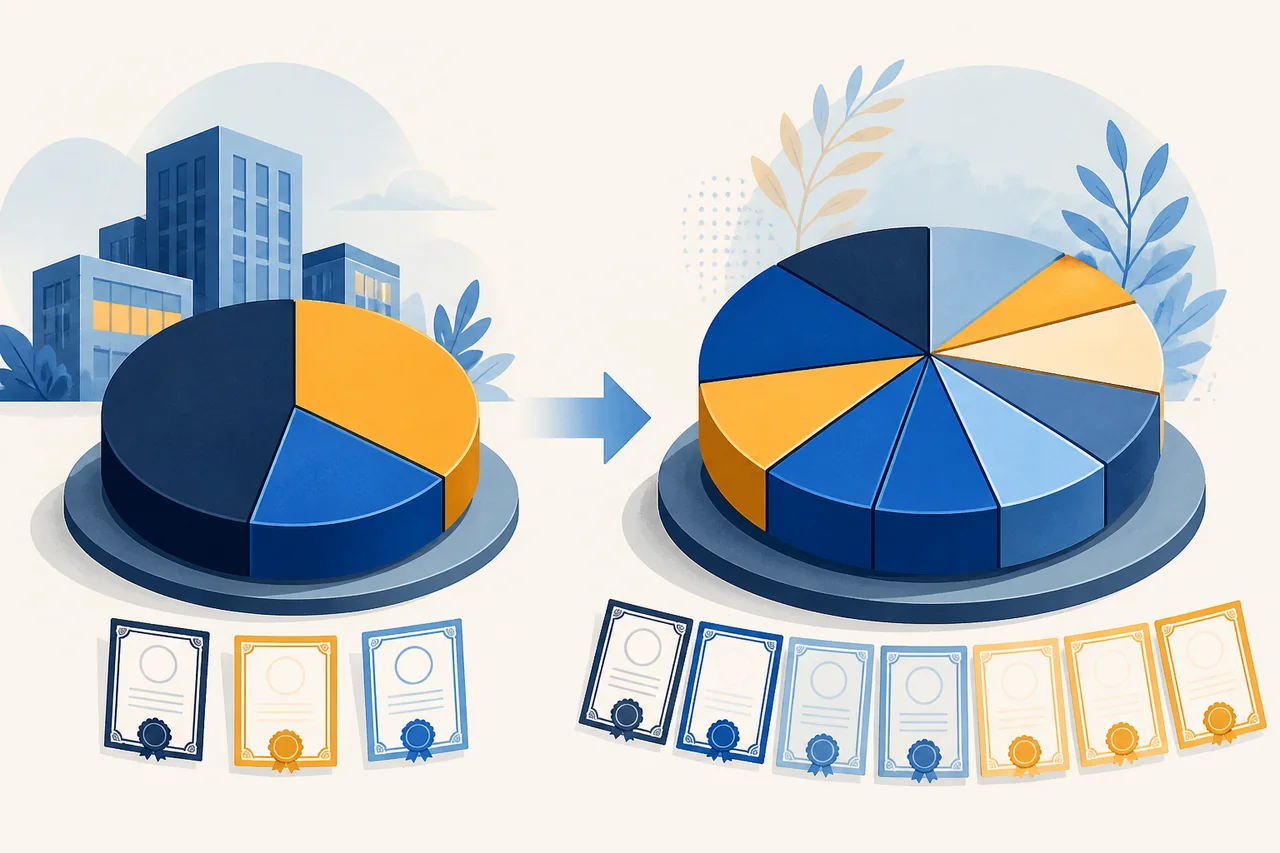
When the share count grows, how much does your slice shrink?
Share prices often fall sharply on the day a company announces a stock offering. New shares mean the same company is divided among more shares, so each existing shareholder's ownership percentage and earnings per share can fall. This is dilution.
Not all dilution has the same effect. Depending on the issue price and how the money is used, an offering can hurt existing shareholders or benefit them over time. This guide covers the routes to dilution, how ownership and per-share value change, and what to check in filings, with hypothetical numbers.
How dilution happens
The most direct route is a share offering. In a rights offering, existing holders can buy new shares in proportion to their stakes and protect their percentage; in a public offering or private placement, shares go to new investors and existing ownership percentages fall.
Convertible bonds and warrants are potential dilution that may turn into shares later. Stock options and restricted stock add shares a little each year. IAS 33's diluted EPS includes these potential shares, so the gap between basic and diluted EPS is a gauge of dilution pressure ahead.
Ownership and per-share value after an offering
In the hypothetical example below, a company whose shares trade at $10 issues 2.5 million new shares at $8, a 20% discount, raising $20 million. The table follows a shareholder who already owns 1 million shares.
| Item | Before | After | Change |
|---|---|---|---|
| Shares outstanding | 10.0 million | 12.5 million | +25% |
| Shareholder A's shares | 1.0 million | 1.0 million | Unchanged |
| Shareholder A's stake | 10.0% | 8.0% | -2.0 pts |
| Company value (simple sum incl. proceeds) | $100 million | $120 million | +$20 million |
| Value per share (simple) | $10.00 | $9.60 | -4.0% |
Issuing shares below the market price reduces value per share even after adding the cash raised. The bigger the discount, the bigger the loss for existing holders.
Purpose and use of proceeds
Two offerings of the same size can have very different outcomes depending on how the money is used. Capital invested in high-return projects or growth can produce profits that more than make up for dilution within a few years. Money used to repay debt or plug operating shortfalls can signal that the business is not generating enough cash on its own.
Registration statements and prospectuses describe the intended use of proceeds. Note how much is earmarked for capital spending, working capital, debt repayment, or acquisitions, and check later 10-Qs and 10-Ks to see whether the money was used as planned.
Frequent misunderstandings
"Every offering is bad news" overlooks cases where capital flows into good investments. A growing company that raises equity close to market price and invests it in high-return projects can increase shareholder value over time.
"No new shares today means no dilution" is also wrong. Convertibles with conversion prices that reset lower if the share price falls can mean more shares will be issued the further the price drops. Watch the potential share count, not just today's.
The steady drip of stock compensation
Stock-based compensation rarely causes a single big jump, but some companies add 1% to 3% to their share count every year. As a hypothetical example, 2% annual dilution compounds to about 10.4% more shares after five years, all dividing the same company.
Many companies offset this with buybacks. The share count may stay flat, but cash that could have gone to shareholders is in effect funding employee compensation, so compare buyback spending with stock-compensation expense.
What to check in filings
Investor.gov's guide to the 10-K and 10-Q points to the financial statements and notes, where share counts and EPS details are disclosed. A sensible sequence:
- In the offering announcement or prospectus, check the structure, number of shares, issue price and discount, and who receives the shares.
- Read the use-of-proceeds section and note amounts for capital spending, working capital, debt repayment, and acquisitions.
- For convertibles, check the conversion price, any reset provisions, and when conversion becomes possible.
- In the EPS note, compare basic and diluted EPS and review the potential shares listed.
- Track in later filings whether proceeds were used as planned and whether the investment is producing profit.
Limits of the dilution math
The per-share value in the table assumes the market values the cash raised at exactly its face amount. Actual share prices move by more or less depending on how investors judge the plan for the money, the discount, and supply and demand for the shares.
The figures here are hypothetical. For real decisions, check the latest filings, checking how recent each one is and weigh the size of the dilution against the profit the new capital could generate.