The question each statement answers
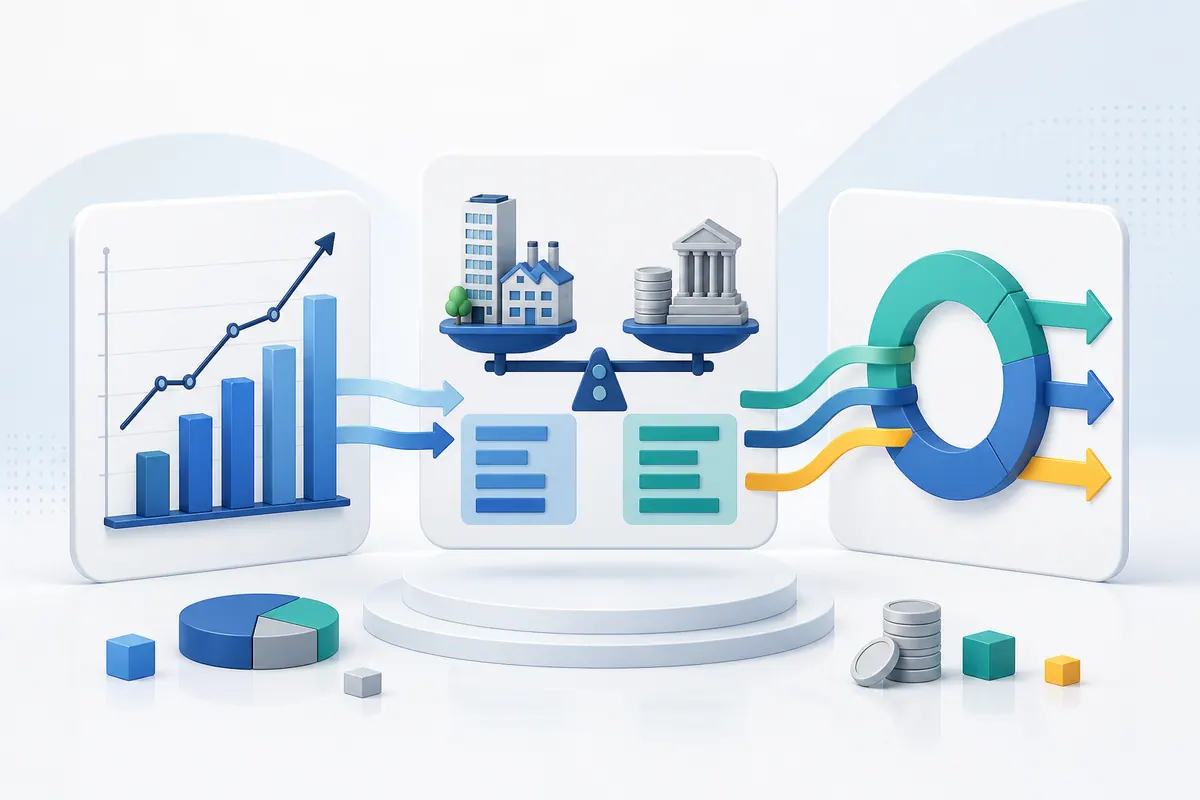
The income statement, balance sheet, and cash-flow statement answer different questions. The income statement covers performance over a period, the balance sheet lists resources and obligations at a point in time, and the cash-flow statement tracks actual cash movement. Reading only one can hide a profitable company with weak cash or an asset-rich company with heavy obligations.
Find the operating result
On the income statement, move from revenue to gross profit and operating profit. Sales can rise while discounts or input costs prevent operating earnings from improving. Non-operating gains, losses, and taxes may change net income substantially, so separate the recurring business result from other items.
Read financial capacity
The balance sheet requires more than a comparison of cash and debt. Receivables growing faster than sales or inventory remaining unsold can tie up working capital. Debt maturities, interest rates, goodwill, and other intangible assets also help describe the company’s financial flexibility.
Use cash flow as a check
Operating cash flow shows whether earnings are turning into cash. Investing cash flow records equipment, acquisitions, and asset sales, while financing cash flow covers borrowing, repayment, dividends, and buybacks. A positive or negative sign has no fixed meaning without the reason behind it and the pattern across several periods.
Connect the three statements
Suppose revenue and net income rise while operating cash weakens. Receivables and inventory may explain the gap. If debt and capital spending also increase, the company may be funding expansion, but the next question is whether future cash generation can support that plan.
Read footnotes and several periods
Definitions and accounting policies live in the footnotes. Compare the latest period with prior years, then read risk factors and management discussion in the original filing. Connecting the statements means investigating inconsistent signals, not collecting only the numbers that look favorable.