The choices in capital allocation
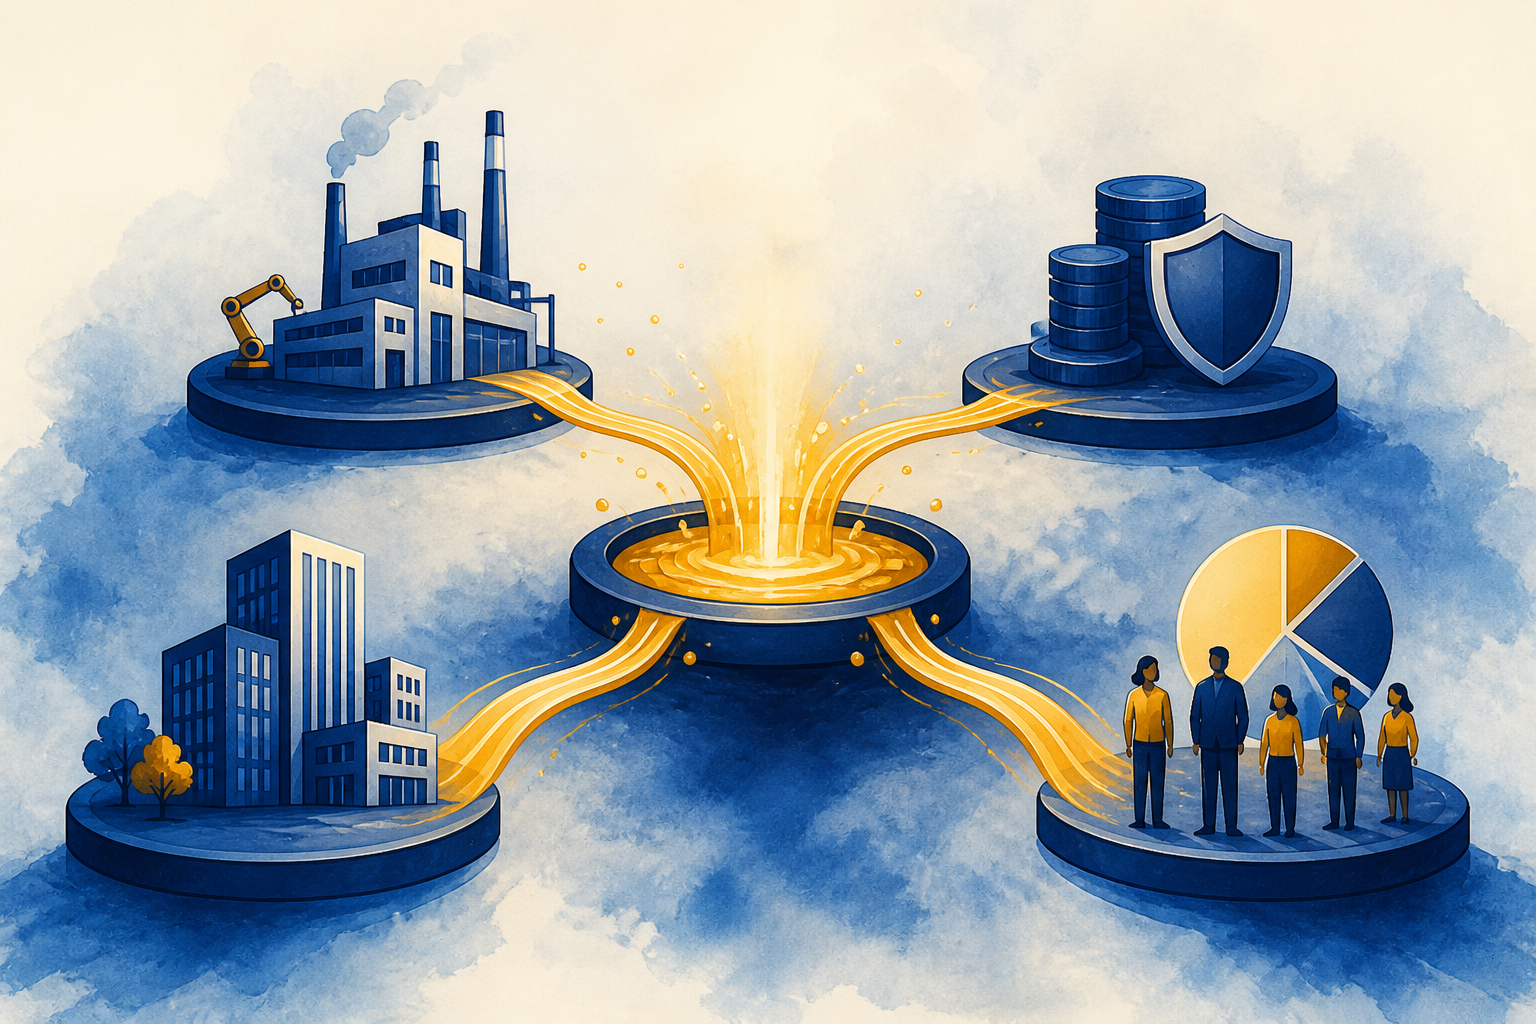
Capital allocation is the process of deciding where operating cash and raised funds should go. Investment, R&D, debt repayment, acquisitions, dividends, and buybacks affect growth and risk differently.
Review reinvestment
Review actual execution and post-investment results rather than announcements alone. Ask what an acquisition did for revenue and cash flow, whether distributions weakened the balance sheet, and whether essential investment continued.
Debt and shareholder returns
Check return targets, cost of capital, cash policy, reinvestment priorities, purchase prices, and impairment charges. Decisions made through both strong and weak cycles provide useful context.
Acquisition price and integration
Capital allocation is best judged as a record of repeated choices. Consider whether decisions strengthen business and financial flexibility or mainly serve a short-term share-price objective.
A hypothetical company
A hypothetical company may generate 100 of operating cash, but whether it should expand a plant, repay debt, pay a dividend, or repurchase shares depends on available opportunities and the cost of capital. Reinvestment can make sense when attractive projects exist; otherwise returning or retaining cash may be preferable. No single choice is always best.
Trace the cash in filings
Trace capital spending, acquisition payments, debt repayment, dividends, and buybacks across several years. Check whether the share count actually fell, whether operating results improved after an acquisition, and whether reinvested capital earned more than its cost. Give more weight to executed results than to management promises.