What research spending includes
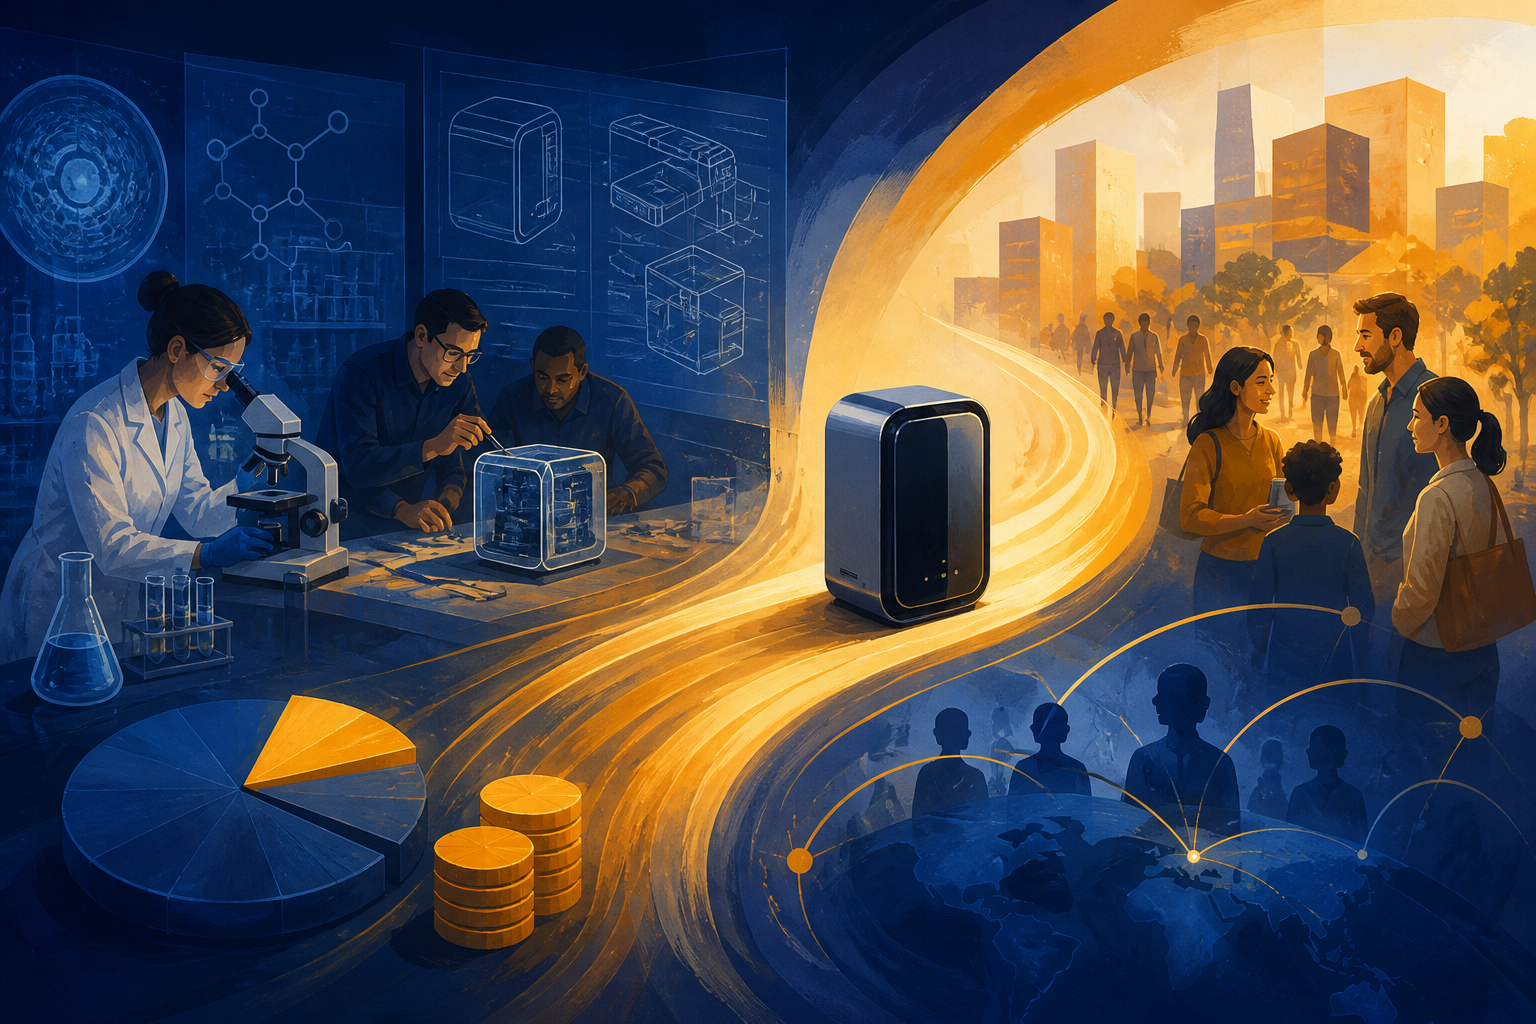
Research and development spending funds new products, technology, processes, or service improvements. It can reduce current profit while creating future revenue or advantage, so size alone is not a quality measure.
Expense recognition and capitalization
Review R&D as a share of revenue, its multi-year trend, and how quickly research becomes products and customers. Rising spending without launches or better gross margins deserves further questions.
Why company comparisons are hard
Accounting rules may capitalize some development costs, so check expense and capitalization policies and amortization periods in the notes. Patent counts alone do not prove commercialization or durability.
The delay before results appear
R&D is a long-term investment with delayed and uncertain results. Connect spending with the problem addressed, validation stages, funding durability, and evidence of adoption.
A hypothetical distinction
Suppose Company A expenses research-stage spending immediately while Company B capitalizes qualifying development spending. The same cash outlay can produce different current profit and asset balances, so comparing R&D as a percentage of sales without accounting context can mislead. First align the accounting rules and capitalization criteria.
Review policies and notes
Filings can disclose how research and development are classified, what marks a completed development stage, the amortization period, and impairment reviews. Whether higher spending becomes a product or revenue may require later-period evidence. Patent counts or headcount alone do not establish economic success.