What EPS answers
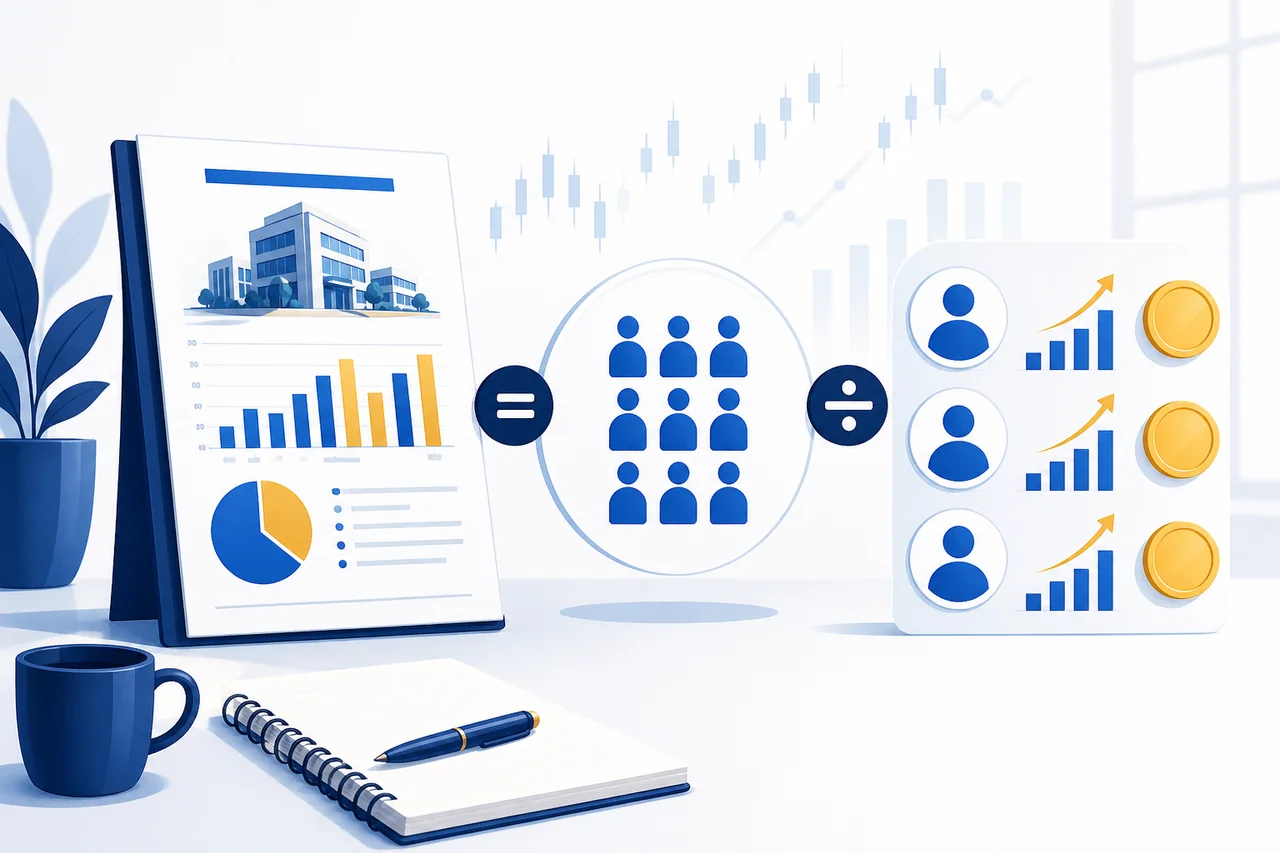
Earnings per share converts a period's profit into the amount attributable to one share. That makes companies of different sizes easier to compare, but an increase in EPS does not by itself prove that the underlying business improved. Both the earnings in the numerator and the share count in the denominator can change.
Basic and diluted EPS
Basic EPS uses the weighted-average common shares actually outstanding. Diluted EPS also considers instruments such as convertible debt and employee options that could become common shares. A wide gap between the two deserves attention because potential issuance may reduce the portion of future earnings attached to each existing share.
Inspect earnings quality
Start by separating recurring operations from an asset sale, unusual tax benefit, valuation gain, or another one-off item. When revenue and operating profit are flat but EPS jumps, the explanation may sit outside the core business. Compare operating cash flow as well to see whether accounting profit is turning into cash.
Connect the share count
A buyback can raise EPS by reducing shares even when total profit does not grow. An equity offering or stock compensation can work in the opposite direction. Put the change in net income beside the change in weighted-average shares so that operating progress is not confused with a financing decision.
A simple comparison
Suppose net income rises from 10 billion to 10.8 billion, an 8% increase, while the share count falls 10%. EPS rises roughly 20%, but only part of that change came from the business. Conversely, profit can rise 15% while EPS declines if the share count expands by 20%.
A filing review order
Review net income, the EPS footnote's numerator and denominator, potentially dilutive securities, and the cash-flow statement in that order. Compare several periods and reconcile any adjusted EPS presented by management with the accounting measure. EPS is most useful as a prompt to investigate durability and ownership per share.