Why sensitivity analysis is used
Valuation sensitivity analysis tests how much an estimated company value changes when its assumptions change. It is designed to show uncertainty across conditions rather than present one precise answer.
Separate the key assumptions
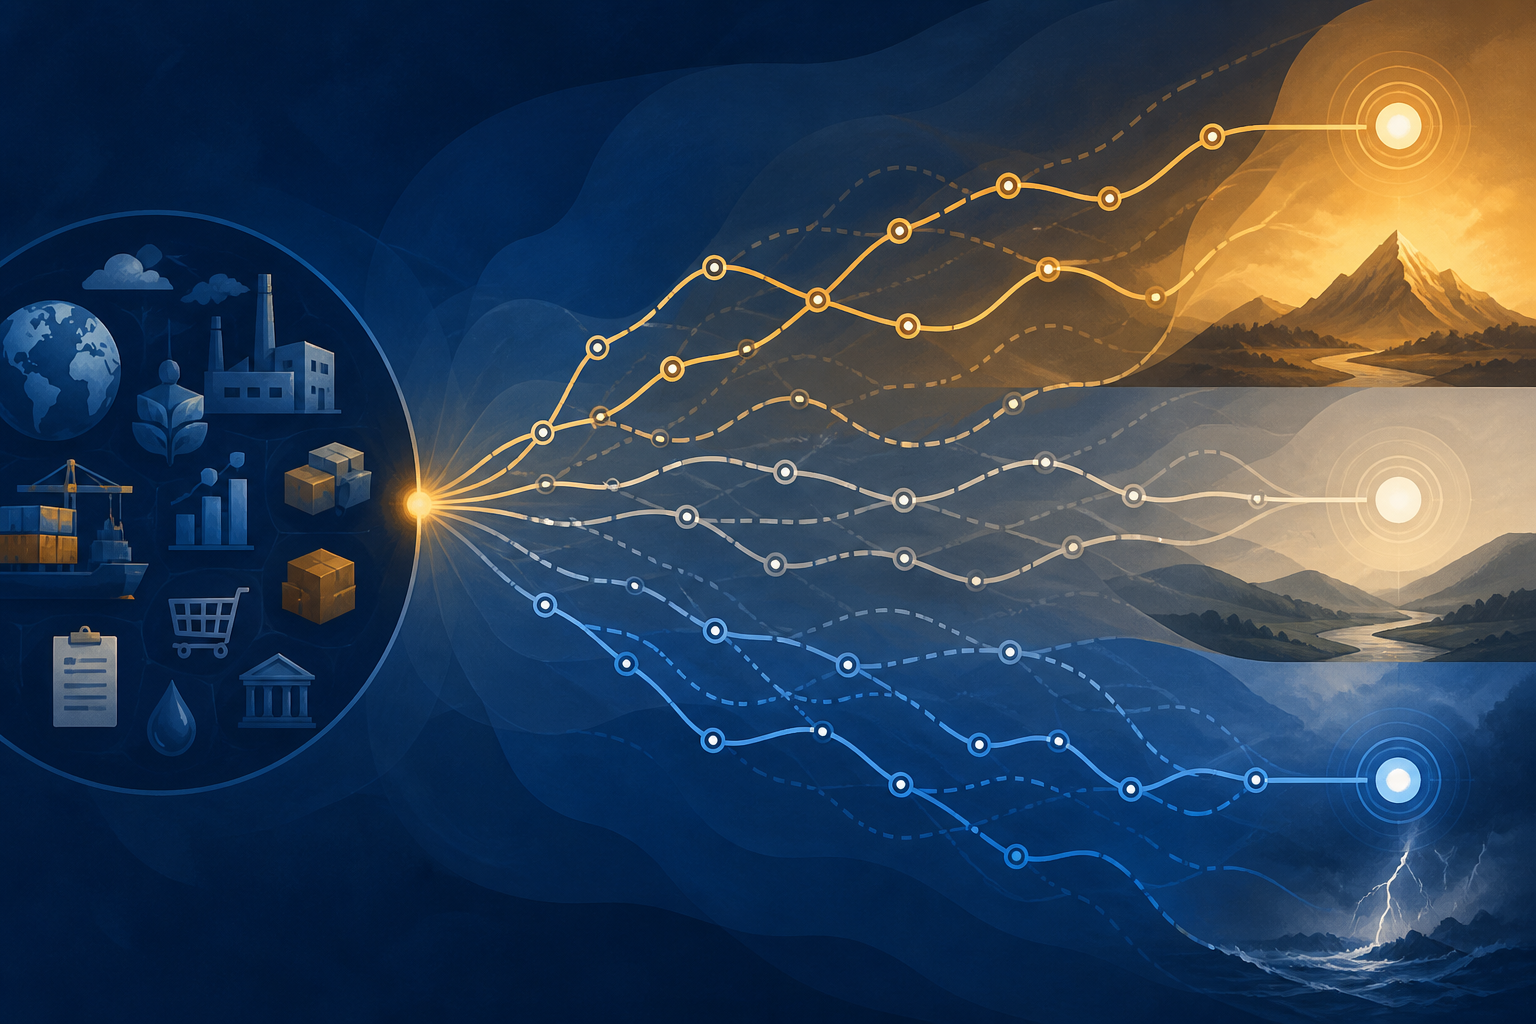
Revenue growth, operating margin, taxes, capital spending, discount rate, and terminal growth can materially affect a cash-flow valuation. Build optimistic, base, and conservative cases and record the evidence for each assumption.
Ranges and scenarios
Large changes from small assumption shifts indicate high uncertainty. Ask whether the business can achieve the growth, how competition and funding costs may change, and how much terminal value drives the result.
Sensitivity is not probability
Sensitivity analysis does not establish a target price. It exposes what is unknown, so the key assumptions and the consequences of being wrong should be explained before relying on the number.
A hypothetical cash-flow example
In a hypothetical valuation model, changing revenue growth and the discount rate changes the output range. A one-percentage-point change in growth need not have the same effect as a one-point change in the discount rate. Explain each variable’s plausible range and interactions; changing many inputs at once can hide what drove the result.
Document the evidence for assumptions
For base, optimistic, and downside cases, connect assumptions to filings, industry evidence, or historical results. A sensitivity table shows how outputs change when assumptions change; it does not give the probability of each scenario or an intrinsic share price. Record the date and calculation method so actual results can later be compared with the assumptions.