The timing between profit and cash
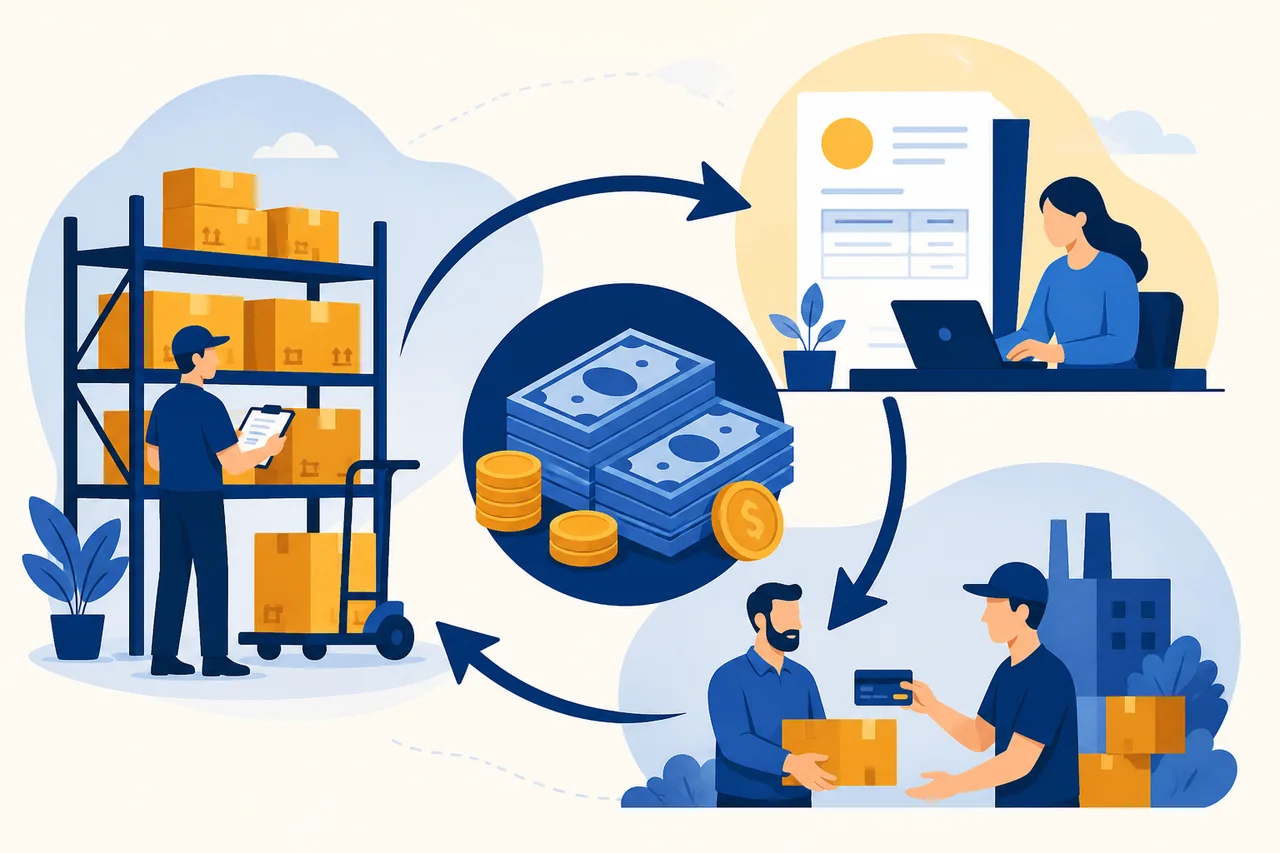
Working capital describes how cash becomes tied up and released during ordinary operations. Funds sit in inventory and receivables between production, sale, and collection, while payables delay part of the cash outflow to suppliers. These timing differences are a common reason why income and operating cash flow diverge.
Read receivables
Receivables growing faster than revenue may indicate slower collection or looser terms. Review days sales outstanding, aging, loss allowances, and customer concentration. A seasonal shipment or one large contract can create a temporary increase, so compare equivalent quarters and several years.
Inventory and payables
More inventory can prepare a company for a launch or busy season, but it can also signal weaker demand and obsolescence. Rising payables can support cash temporarily, yet the cause may be delayed supplier payments. Interpret all three items inside the operating process rather than labeling each balance as good or bad by itself.
Healthy and unhealthy growth
During growth, receivables and inventory can make operating cash flow temporarily weak. The pattern becomes more concerning when working capital repeatedly grows faster than sales while discounts or loss allowances also rise. Cutting inventory too aggressively can create stockouts and sacrifice future sales.
The cash conversion cycle
The cash conversion cycle adds inventory days and receivable days, then subtracts payable days. Fifty plus forty minus thirty implies roughly sixty days of funding tied to operations. The reasons for each change and the bargaining structure of the industry matter more than the isolated total.
A quarterly review order
Each quarter, place revenue growth, changes in receivables, inventory and payables, operating cash flow, and relevant notes in one worksheet. Under the indirect cash-flow method, these movements reconcile profit with cash. Working capital is therefore a window into liquidity, revenue quality, and operating discipline.